Top Audit Firm in Singapore for Reliable Financial Reporting and Compliance Services

Choosing a top audit firm in Singapore begins with a question older than the profession itself: can this partner stand in front of a regulator, a board, and a set of shareholders and say that the numbers are true. Singapore has built its standing as a financial capital on that single promise. The Accounting and Corporate Regulatory Authority, known to every practitioner as ACRA, inspects the work of public accountants with a diligence that rewards those who prepare thoroughly and punishes those who do not.

History has shaped this culture. When Singapore separated from Malaysia in 1965, the young republic needed international capital, and international capital needed assurance. Within a decade, the leading audit houses had set up operations along Shenton Way, and local firms learned to match them in rigour. That inheritance still defines the market today.

What Sets the Leading Practices Apart

A top audit firm in singapore earns its reputation through three habits: technical depth, early engagement, and plain-language communication. The technical partner must understand Singapore Financial Reporting Standards, the updates issued each year, and the interplay with IFRS where a client reports to a foreign parent. Early engagement means sitting with management in the third quarter, before the year-end, to raise issues while they can still be corrected.

Plain-language communication is where most firms fall short. A management letter written in jargon serves no one. The finest senior partners in the country can explain a complex revenue-recognition issue to a family-business chairman in ten minutes. That skill takes twenty years to develop and cannot be taught from a textbook.

Services the strongest firms provide

  • Statutory audit
  • Annual financial statements for private and listed companies
  • Group consolidation for multinational structures
  • Compliance and advisory
  • Corporate tax filings and GST reviews
  • Transfer pricing documentation
  • Special engagements
  • Due diligence for mergers and acquisitions
  • Forensic reviews and internal controls assessments

The Singapore Regulatory Landscape

Every practitioner here works under the gaze of ACRA, the Inland Revenue Authority of Singapore, and, for listed entities, the Singapore Exchange. The three regulators do not always speak with a single voice, and a seasoned auditor translates their expectations for the client. A small manufacturer in Tuas may need guidance on a new IRAS ruling one month and on an ACRA disclosure requirement the next.

The Code of Professional Conduct and Ethics, issued by the Institute of Singapore Chartered Accountants, governs every independence question. A top audit firm in singapore maintains a separate team to monitor threats to independence and rotates engagement partners on a strict five-year cycle for public-interest entities. No shortcut exists on this point.

Lee Kuan Yew once observed, “If you do not have a culture which encourages enterprise, you will always be at the bottom of the league.” The same logic applies inside a firm. The practices that encourage junior staff to raise uncomfortable questions end up spotting issues that a complacent team would miss.

How Fees Are Structured and What to Expect

Audit pricing in Singapore varies with complexity. A small private company with simple operations pays between S$5,000 and S$12,000 for a statutory audit. A mid-sized group with two or three subsidiaries expects fees in the range of S$25,000 to S$60,000. A Catalist-listed company crosses S$120,000, and a main-board listing with foreign operations can reach half a million. These figures move with scope, not with discounts.

A prospective client should ask three questions before signing an engagement letter:

  • Which partner will sign the audit report, and how many hours will that partner personally commit?
  • What is the firm’s track record of ACRA practice-monitoring reviews in the past three inspection cycles?
  • Does the team include a specialist in the client’s industry, whether shipping, fintech, or food manufacturing?

The answers reveal the depth of the practice faster than any brochure.

The Human Side of the Audit

Numbers alone do not build a business. An auditor who understands the human story behind the accounts becomes an adviser, not a box-ticker. A senior partner who has walked the factory floor of a Jurong plastics producer, asked about the quality-control logs, and sat through a conversation about succession in a founding family knows where the audit risks really live.

That instinct cannot be codified. A young associate learns it by observation, one engagement at a time, across a decade of practice. The firms that invest in training and mentoring produce that generation of auditors; the firms that chase headcount do not.

Final Thoughts

A Singapore company choosing its auditor chooses a partner for the long run. The relationship survives management changes, regulatory shifts, and occasionally a crisis that tests every clause of the engagement letter. Working with a respected Singapore auditors practice means working with a team that treats the signature on the audit report as a matter of personal integrity, not merely a commercial deliverable. For any business weighing its options, the decision to appoint a top audit firm in Singapore shapes the board’s confidence, the regulators’ trust, and the company’s standing for years to come.

Warehouse Management System Explained: Functions and Use Cases

The warehouse management system emerged from necessity, born in an era when the sheer volume of goods moving through distribution centres overwhelmed human capacity to track and manage them effectively. In the 1970s, as computerisation began infiltrating business operations, warehouse managers recognised that their facilities had become bottlenecks in supply chains designed for speed. What started as rudimentary software tracking bin locations has evolved into sophisticated platforms that orchestrate every movement within four walls, from the moment goods arrive until they depart for their final destinations. These systems now represent the difference between warehouses that merely store products and those that function as strategic assets in competitive commerce.

The Core Architecture of Control

At its foundation, a warehouse management platform serves as the central nervous system for storage operations. It directs where items go when they arrive, guides workers to their locations when orders require fulfilment, and maintains precise records of every transaction. But this description, though accurate, fails to capture the orchestration complexity involved.

Consider a single pallet arriving at a receiving dock. The system must verify the shipment against purchase orders, assign storage locations based on product characteristics and demand patterns, generate put-away instructions for forklift operators, update inventory counts across multiple databases, and alert quality control if inspection is required. All of this happens in seconds, repeated hundreds or thousands of times daily.

Singapore’s port-adjacent warehouses demonstrate this complexity at scale. Containers arrive from vessels, their contents destined for dozens of different customers. The WMS software must disaggregate these mixed shipments, route items to appropriate zones, and coordinate with customs systems before goods can move to their next destinations. The choreography rivals ballet in its precision.

Receiving and Put-Away Operations

The receiving process sets the tone for everything that follows. Errors introduced at this stage compound throughout the warehouse lifecycle. Modern warehouse control systems employ multiple verification methods to ensure accuracy:

  • Barcode scanning that matches incoming goods against expected shipments 
  • Dimension and weight capture using automated systems 
  • Quality inspection workflows triggering holds when necessary 
  • License plate number generation creating unique identifiers for tracking
  • Cross-docking logic identifying items that can bypass storage entirely

The put-away function determines where items reside within the facility. Simple warehouses might use fixed locations, but sophisticated operations employ dynamic slotting algorithms that constantly optimise placement. Fast-moving items migrate toward packing stations. Slow movers shift to less accessible areas. Heavy items stay at ground level. The system makes thousands of these micro-decisions, creating efficiency that manual management cannot match.

Picking and Order Fulfilment

When orders arrive, the warehouse management solution transforms from inventory custodian to logistics coordinator. It must analyse orders, determine optimal picking sequences, assign tasks to available workers, and coordinate multiple orders moving through the facility simultaneously.

Singapore’s e-commerce fulfilment centres showcase advanced picking methodologies. During peak periods, a single facility might process thousands of orders hourly. The system employs wave picking, where multiple orders are batched together. Workers pick items for many orders simultaneously, with sorting happening later. This approach reduces travel time dramatically compared to sequential order picking.

Alternative strategies serve different needs:

  • Zone picking assigns workers to specific warehouse areas, with items moving between zones 
  • Batch picking groups similar orders to minimise movement 
  • Pick-to-light systems use illuminated displays guiding workers to correct locations 
  • Voice picking employs audio instructions, freeing workers’ hands and eyes

Inventory Accuracy and Cycle Counting

The warehouse inventory system maintains theoretical perfection in its database. Reality proves messier. Products get damaged, mislabelled, or misplaced. Theft occurs. Recording errors accumulate. Without systematic verification, the gap between digital records and physical reality widens until the system becomes unreliable.

Cycle counting addresses this challenge through continuous verification. Rather than annual wall-to-wall inventories that shut down operations, small portions of inventory are counted daily. High-value items receive frequent verification. Fast-moving products get counted regularly to catch errors quickly. The system schedules these counts, generates instructions for workers, and flags discrepancies requiring investigation.

Labour Management and Productivity

Beyond managing inventory, modern systems increasingly manage people. They track individual worker productivity, identifying who completes tasks efficiently and who struggles. This data serves multiple purposes, from recognising top performers to identifying training needs.

Singapore’s logistics sector, facing persistent labour shortages, uses these capabilities extensively. The automated warehouse system routes tasks to workers based on their location, skill level, and current workload. It estimates completion times for different task types and adjusts assignments dynamically as conditions change. Some facilities gamify the process, with leaderboards and performance bonuses creating competitive motivation.

Integration With Broader Operations

No warehouse operates in isolation. The warehouse management system must communicate constantly with transportation management systems coordinating inbound and outbound shipments, inventory management systems tracking stock across multiple facilities, enterprise resource planning systems managing financial records, and customer-facing platforms displaying availability and shipping status.

These integrations create challenges and opportunities. When systems communicate seamlessly, information flows without manual intervention. Orders placed online instantly reserve inventory, generate picking instructions, and schedule shipments. But integration failures create chaos, with orders processing against phantom inventory or shipments departing without proper documentation.

The Human Element Persists

Despite increasing automation, warehouses remain fundamentally human workplaces. The most sophisticated warehouse management system fails if workers cannot or will not use it effectively. Successful implementations balance technological capability with human factors, creating interfaces that guide rather than confuse, that assist rather than dictate, and that recognise the expertise workers bring to their roles.

Real Estate Consultancy Services: Expert Advice for Better Decisions

You’d think that real estate consultancy services would be something only the wealthy need, those with portfolios thick as novels and properties scattered across continents, but that’s not the truth of it at all. Even ordinary people trying to make their way in Singapore’s bewildering property market can benefit from proper advice. I learned this the hard way, after making mistakes that could have been avoided if I’d known such services existed and understood what they actually do.

What Are These Consultancy Services Anyway?

Real estate consultancy services are essentially professional advice from people who’ve spent years understanding property markets, regulations, trends, and all the complicated machinery that turns when you’re buying, selling, leasing, or investing in real estate. They’re not estate agents, though people confuse the two. Estate agents help you transact. Consultants help you think, plan, strategise, and avoid the pitfalls that swallow up the unprepared.

In Singapore, where property dominates conversation at dinner tables and coffee shops, where people check property prices the way others check the weather, having expert guidance isn’t luxury. It’s sense. The market here is complex, regulated, expensive, and unforgiving to those who don’t understand its rhythms.

The Services They Actually Provide

When you engage property consultancy services, you’re not just paying for someone to nod and agree with your plans. You’re paying for expertise, for knowledge accumulated through years of watching markets rise and fall, through studying regulations that change faster than you can keep up with.

These services typically include:

  • Market analysis and feasibility studies to determine if your plans make financial sense
  • Investment strategy development for those looking to build property portfolios
  • Due diligence services to uncover problems before you commit your money
  • Regulatory compliance advice to navigate Singapore’s complex property laws
  • Portfolio management for those with multiple properties
  • Exit strategy planning for when it’s time to sell

According to industry practice, “professional real estate consultancy provides objective analysis based on data, market knowledge, and regulatory expertise, enabling clients to make informed decisions.” That’s the official language, but what it means is simpler: they help you avoid expensive mistakes.

Why You Might Actually Need This

I used to think I could figure everything out myself. Read some articles, browse property websites, talk to friends who’d bought flats, and that would be enough. It wasn’t. Singapore’s property market has layers upon layers of complexity. There’s the Additional Buyer’s Stamp Duty to consider, cooling measures that change with government policy, loan-to-value ratios that affect financing.

Then there’s timing. When to buy, when to sell, when to hold. There’s location analysis, understanding which neighbourhoods will appreciate. There’s the legal side, the contracts and clauses, the hidden obligations. It’s overwhelming, honestly, and trying to master it all yourself while working full-time is nearly impossible.

The Money Question

Real estate consultation services cost money, obviously. Nothing’s free in Singapore, least of all expertise. But here’s what I’ve learned: the cost of bad decisions in property far exceeds the cost of good advice. Buy the wrong property and you might lose tens of thousands. Overpay because you didn’t understand market conditions and you’ve thrown money away.

The fees vary depending on what you need. A simple consultation might cost a few hundred pounds. Comprehensive services for major investments run into thousands. But consider what you’re spending on the property itself, the hundreds of thousands or millions, and suddenly paying for professional guidance seems less like an expense and more like insurance.

Finding the Right Consultant

Not all real estate consultancy services are equal. Some consultants have deep market knowledge. Others specialise in particular property types or investment strategies. Some are excellent with residential properties but lost when it comes to commercial or industrial. You need to find someone whose expertise matches your needs.

Ask questions before engaging anyone:

  • How long have they been practising in Singapore?
  • What’s their track record with situations like yours?
  • Can they provide references from previous clients?
  • Do they have relevant professional qualifications?
  • How do they charge for their services?

Don’t be shy about this. You’re not being rude asking these things. You’re being sensible. Anyone offended by reasonable questions isn’t someone you want advising you on major financial decisions.

What They Cannot Do

Here’s something important: real estate consultancy services provides advice and analysis, but they cannot make decisions for you. They cannot guarantee outcomes. They cannot eliminate risk entirely. The Singapore property market, like any market, has uncertainties. Consultants can help you understand and manage these uncertainties, but they cannot make them disappear.

If someone promises guaranteed returns or swears their advice cannot possibly go wrong, walk away. Good consultants present options, explain risks, provide data, and help you think through decisions. They don’t make wild promises.

The Peace of Mind Factor

Perhaps the greatest value of property consultancy services is something harder to quantify: peace of mind. Knowing you’ve done your due diligence, that you’ve sought expert opinion, that you’ve considered angles you wouldn’t have thought of yourself brings comfort. Property decisions weigh heavily. They affect your finances, your family’s future, your retirement plans. Having professional guidance doesn’t guarantee success, but it means you’ve given yourself the best chance possible.

Making Your Choice

Whether you’re buying your first flat, investing in commercial property, or planning your exit from the market, real estate consultancy services offer expertise that can save you money, time, and considerable stress. It’s not weakness to seek help. It’s wisdom. And in Singapore’s demanding property market, wisdom is something we all could use more of when making decisions about real estate consultancy services.

Education Loan: Flexible Financing for Local & Overseas Studies

An education loan represents a calculated gamble on the future, a financial instrument that has quietly reshaped Singapore’s educational landscape and determined the trajectories of countless lives. Behind the sterile banking terminology lies a more compelling story: how families navigate the widening gap between educational aspirations and financial reality, and how a nation built on meritocracy confronts the uncomfortable truth that talent alone no longer guarantees access to higher learning. The cost of university education has escalated dramatically, with local university fees ranging from £8,000 to £30,000 annually and overseas institutions demanding £20,000 to £60,000 per year.

The Origins of Educational Debt

Singapore’s education financing system evolved alongside its economic transformation. In earlier decades, government subsidies and modest fees made tertiary education relatively accessible. But as the economy sophisticated and global competition intensified, universities expanded offerings and infrastructure. The bills followed. By the early 2000s, families began confronting a new reality: even admission to prestigious institutions no longer guaranteed affordable access.

The education loan emerged as the solution, a private market response to a public need. What developed was a complex ecosystem of lending products, each with its own terms and long-term implications for borrowers.

The Mechanics of Educational Financing

An education loan in Singapore operates through established frameworks shaped by both market forces and regulatory oversight. Understanding these mechanisms requires examining what lenders offer and what they demand in return.

Typical education loan structures include:

  • Loan amounts ranging from £5,000 to £150,000, depending on course and institution 

  • Interest rates between 3.5% and 8% annually for local studies 

  • Overseas education loans carrying rates of 5% to 10% annually 

  • Repayment periods extending from 5 to 20 years 

  • Grace periods of 6 to 12 months post-graduation before repayment begins 

  • Options for parents or students as primary borrowers

The distinction between local and overseas education loans proves significant. Lenders view overseas studies as higher risk, reflected in elevated interest rates and stricter approval criteria. A student pursuing medical studies at National University of Singapore faces different financing terms than one attending a comparable programme in the United Kingdom or United States.

The Application Architecture

Securing an education loan requires navigating bureaucratic requirements that test family resources before a single pound is disbursed. The documentation demands tell their own story about whom the system trusts.

Required materials typically include:

  • Proof of admission to recognized educational institutions 
  • Identity documents for borrower and guarantor 
  • Income verification for parents or guarantors 
  • Bank statements demonstrating financial history 
  • Academic transcripts and qualification certificates 
  • Detailed breakdown of tuition fees and living expenses

For families with stable employment and documented income, these requirements pose manageable hurdles. But for those in informal sectors or with irregular earnings, the documentation barrier can prove insurmountable.

The Guarantor Imperative

Most education loans require guarantors, typically parents, who assume legal responsibility for repayment should the student default. This requirement embeds educational debt within family structures, creating dynamics that extend far beyond financial obligation.

Consider the calculation a parent makes: signing as guarantor means pledging one’s own financial security against a young person’s uncertain future. If the graduate secures lucrative employment, the loan becomes manageable. If career prospects disappoint, the guarantor faces potential financial ruin.

I have documented numerous cases where guarantors, often parents in their fifties or sixties, found themselves servicing children’s education loans from retirement savings. The education loan transforms family relationships, introducing obligations and tensions that persist long after graduation.

The CPF Education Scheme

Singapore offers a government alternative through the CPF Education Scheme, allowing members to use Central Provident Fund savings for approved courses. This option carries a concessionary interest rate of 2.5% annually, significantly below commercial rates. However, the borrowed amount plus accrued interest must be repaid to the CPF account, ensuring retirement adequacy remains protected.

The scheme’s limitations include restrictions on approved institutions and courses, maximum loan amounts, and the requirement that borrowers possess sufficient CPF balances. These constraints mean many students must supplement with commercial education loans.

The Burden of Servicing

The mathematics of loan repayment shape post-graduation lives in profound ways. A graduate with £60,000 in education loan debt at 6% interest over ten years faces monthly repayments of approximately £665. For a young professional earning £3,500 monthly, this represents nearly 20% of gross income, significantly constraining housing choices, marriage timing, and other life decisions.

The Total Debt Servicing Ratio framework applies to education loans, limiting how much graduates can subsequently borrow for housing or other needs. A substantial education loan balance can delay property purchases by years, affecting wealth accumulation trajectories across entire lifetimes.

Strategic Considerations

Families considering education loans must think beyond immediate educational access to long-term financial implications:

  • Compare effective interest rates across multiple lenders 
  • Calculate total repayment amounts over full loan tenures 
  • Evaluate realistic post-graduation earning potential in chosen fields 
  • Consider whether overseas study premiums justify additional debt burdens 
  • Explore scholarship opportunities before committing to loans 
  • Understand grace period terms and early repayment options

The Larger Questions

The proliferation of education loans reflects uncomfortable truths about contemporary Singapore. Educational access increasingly depends on family willingness to assume debt. Merit matters, but so does financial backing. The education loan has become essential infrastructure in a society committed to educational excellence yet struggling with its escalating costs.

Behind every education loan application lies a family’s hopes, calculations, and anxieties about securing better futures through learning, revealing how financial access shapes not just individual opportunities but the very possibility of social mobility itself.

How to Secure a Business Startup Loan and Build Your Future

Starting Out: Why a Business Startup Loan Matters

A business startup loan for new entrepreneurs can be the bridge between a bright idea and a successful enterprise. In Singapore’s competitive economy, funding often determines whether a business takes off or stays on the drawing board. A business startup loan gives founders the resources to cover essential costs such as renting office space, hiring staff, or purchasing equipment. Beyond money, it symbolises belief, a sign that your idea holds promise and that others trust your potential to grow.

What Is a Business Startup Loan?

A business startup loan is financing created to help entrepreneurs launch and sustain their ventures during the early stages. Unlike traditional loans, which often require years of proven revenue, these loans are designed for new business owners with limited financial history but solid plans.

Funds from a business startup loan can be used to:

  • Rent or purchase commercial space
  • Buy machinery, stock, or technology
  • Hire staff or consultants
  • Develop marketing and branding campaigns
  • Manage early cash flow and operating costs

Singapore’s financial sector, supported by government programmes, offers various options for new business owners. As one adviser observed, “Startup financing isn’t just about capital, it’s about confidence in an entrepreneur’s vision.”

Why Entrepreneurs Choose a Business Startup Loan

Starting a business is both exciting and risky. Many entrepreneurs find their savings insufficient to sustain operations through the first year. A business startup loan provides breathing room, helping new companies focus on growth rather than survival.

Benefits of a business startup loan include:

  • Access to Capital: Provides immediate funds for setup and growth.
  • Preserves Personal Savings: Protects your finances from overexposure.
  • Encourages Sustainable Growth: Supports expansion in measured steps.
  • Builds Business Credit: Establishes financial credibility for future borrowing.
  • Predictable Repayments: Fixed instalments simplify cash flow management.

When used wisely, a startup loan becomes more than a financial tool, it builds confidence, stability, and growth.

Types of Business Startup Loans in Singapore

Singapore’s financial ecosystem offers diverse funding options for entrepreneurs.

1. Term Loans

A lump-sum loan repaid over a fixed period with interest. Ideal for major investments such as property or technology.

2. Working Capital Loans

Short-term financing to maintain daily operations and manage recurring expenses like rent or payroll.

3. Equipment Financing

Funds the purchase of machinery or technology, avoiding large upfront costs.

4. Micro Loans for Startups

Smaller loans with quicker approvals and flexible repayment options, suitable for micro-businesses or self-employed founders.

5. Government-Assisted Loan Schemes

Under the Enterprise Financing Scheme (EFS), the Singapore government partners with banks to share lending risks. This ensures that small businesses can access loans that might otherwise be unavailable. As one policymaker put it, “We want every capable entrepreneur to have the chance to turn an idea into reality.”

How to Apply for a Business Startup Loan

Securing a business startup loan requires preparation and organisation. Lenders want evidence that your business is viable and that you can manage the funds responsibly.

1. Develop a Comprehensive Business Plan

Include details on your product or service, market opportunity, and financial forecasts.

2. Determine How Much You Need

Borrow enough to sustain growth, but avoid unnecessary debt.

3. Check Eligibility Requirements

Lenders typically evaluate:

  • At least 30% local ownership
  • Registration with ACRA
  • A clear credit record
  • Solid cash flow and projections

4. Prepare Required Documents

Have these ready:

  • Business registration certificate
  • Financial statements or forecasts
  • Bank statements
  • Identification of owners or directors

5. Compare Lenders and Loan Options

Different institutions offer varying interest rates, terms, and fees. Compare before committing.

6. Submit and Follow Up

Once you’ve applied, maintain open communication. Responding quickly to requests for information can speed up approval.

Common Mistakes to Avoid

New business owners often make errors that hurt their loan applications. Avoiding these pitfalls improves approval chances.

  • Weak Business Plans: Lack of clear projections makes lenders cautious.
  • Overborrowing: Taking too much can strain cash flow.
  • Ignoring Credit History: Poor credit can affect approval.
  • Failing to Compare Offers: Not reviewing lenders may cost you better terms.
  • Unrealistic Expectations: Overconfidence can seem unreliable.

Government Support for Startups in Singapore

Singapore’s government actively supports entrepreneurship through initiatives like Startup SG and the Enterprise Financing Scheme (EFS). These programmes offer both financial and advisory assistance, creating a supportive environment for business growth.

Grants and co-funding opportunities exist for businesses that invest in innovation or digital transformation. As noted in an official report, “Our priority is to help startups grow and contribute to Singapore’s future economy.”

Tips to Strengthen Your Loan Application

  • Keep accurate financial records.
  • Present realistic, well-supported projections.
  • Provide proof of customer demand.
  • Offer collateral when possible.
  • Communicate consistently with lenders.

A professional, transparent approach helps establish trust and increases approval odds.

Final Thoughts: Building Success with the Right Foundation

Applying for a business startup loan is more than a financial move, it’s a statement of intent. It shows belief in your idea and readiness to grow it with discipline. The process requires preparation and patience, but the rewards are significant.

Used effectively, a business startup loan can transform ambition into achievement and lay the foundation for a thriving business.

Why Face Painting Has Become Singapore’s Unexpected Art Form

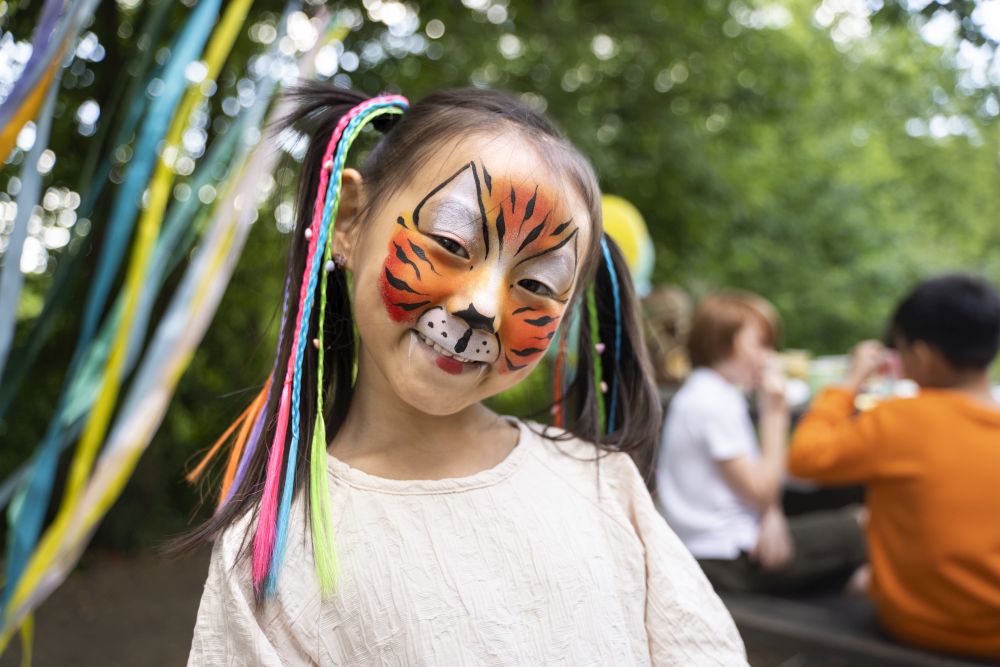
When you hire a face painter Singapore offers for your child’s birthday party, you might assume you are simply booking entertainment. Yet what unfolds is something more complex: a fusion of performance art, cultural expression, and childhood psychology that has quietly evolved into one of the city-state’s most versatile creative professions. Over the past decade, face painting has transcended its origins as mere party decoration to become a sophisticated craft that reflects Singapore’s multicultural identity whilst serving increasingly diverse purposes across the island.

The Science of Childhood Wonder

Face painting operates on principles that child psychologists have long understood. Children experience identity formation through play, and temporarily transforming into a tiger, butterfly, or superhero allows them to explore different aspects of themselves. One veteran face painter in Singapore explained, “When a shy child chooses to become a lion, you can see their posture change. They stand taller. It is not just paint, it is permission to be brave.”

The transformation occurs within minutes, yet the psychological impact extends far beyond the event itself. Photographs capture these altered identities, creating tangible memories that families revisit repeatedly. In Singapore’s documentation-obsessed culture, where every moment seems destined for social media, face painting provides visual spectacle that translates beautifully to photographs whilst offering children genuine, unmediated joy.

Cultural Complexity on Canvas

Singapore’s unique demographic composition creates distinctive demands for face painters working across the island. A single event might host families from Chinese, Malay, Indian, and Western backgrounds, each bringing different aesthetic preferences and cultural sensitivities. Skilled face painters in Singapore have developed expansive repertoires that honour this diversity.

During Chinese New Year celebrations, demand surges for zodiac animals, dragons, and traditional motifs rendered in auspicious colours. Hari Raya events might feature intricate henna-inspired patterns that respect Islamic artistic traditions. Deepavali parties call for designs incorporating rangoli patterns and Hindu symbolism. Meanwhile, Western-influenced birthday parties request superheroes, Disney characters, and contemporary designs that children encounter through global media.

This cultural fluency requires more than technical skill. As one practitioner observed, “You need to understand what each design means to different communities. A butterfly might be universal, but specific colours and patterns carry meanings you must respect.”

The Professional Evolution

What began as a side occupation for art students has matured into a legitimate profession with surprising complexity. Professional face painters in Singapore invest substantially in their craft:

  • Premium materials

Hypoallergenic, FDA-approved paints that withstand Singapore’s humidity and intense heat

  • Continuous training

Workshops covering new techniques, trending characters, and advanced designs that elevate their work

  • Business infrastructure

Liability insurance, proper licensing, and booking systems that manage Singapore’s demanding corporate and private event calendars

  • Artistic development

Many study fine arts, makeup artistry, or theatrical design to enhance their technical capabilities

The economic reality proves surprisingly robust. Experienced face painters singapore residents regularly book can earn respectable hourly rates, particularly for corporate events, large-scale festivals, and premium private functions. The profession offers flexibility that appeals to artists balancing creative pursuits with financial stability.

Beyond Birthday Parties

Whilst children’s parties remain foundational, face painting has expanded into unexpected territories across Singapore. Corporate events employ face painters to attract crowds to exhibition booths, create branded designs featuring company logos, or provide entertainment that softens formal atmospheres. Shopping centres use face painting to increase foot traffic during school holidays and promotional campaigns.

Charity events and community festivals represent another growth area. Face painting stations draw families whilst supporting worthy causes, creating win-win scenarios that benefit both organisers and attendees. One face painter specialising in charity work noted, “These events matter differently. Parents appreciate free quality entertainment, and you are contributing something meaningful beyond commerce.”

The Technical Challenge

Singapore’s climate presents formidable obstacles. Temperatures regularly exceeding 30 degrees Celsius, combined with oppressive humidity, threaten face paint longevity. Professional face painters have adapted through careful product selection, application techniques that account for perspiration, and realistic expectations about duration.

Working outdoors during daytime events compounds these challenges. One practitioner explained, “You learn quickly which products survive Singapore’s conditions. Parents expect designs to last through the party, so you cannot use materials that melt within 20 minutes.”

Speed constitutes another critical skill. Long queues of impatient children require efficient execution without sacrificing quality. Experienced face painters in Singapore can complete simple designs within three minutes and complex pieces within eight, maintaining artistic standards whilst managing throughput that satisfies event organisers.

Health and Safety Considerations

Professional standards have risen considerably as awareness of skin sensitivities has increased. Reputable face painters use only cosmetic-grade paints specifically formulated for skin application, avoiding craft paints or theatrical makeup unsuitable for children. They inquire about allergies, maintain scrupulous hygiene, and employ proper sanitisation between clients.

Parental scrutiny has intensified these requirements. Singapore’s educated, health-conscious families research products and question practitioners about ingredients. This vigilance has elevated industry standards, weeding out casual operators whilst rewarding professionals who invest in premium materials and proper training.

Looking Forward

As Singapore continues developing its arts ecosystem and experience economy, face painting occupies an interesting position. It remains accessible and democratic, requiring no tickets or advance booking at public events, yet delivers personalised artistry that feels exclusive. It bridges high and low culture, applying fine art techniques to popular entertainment.

The profession attracts talented individuals who might otherwise struggle finding viable creative careers in Singapore’s pragmatic economy. It offers artistic expression, human connection, and entrepreneurial possibility within a framework that parents, corporations, and communities readily embrace. Whether transforming a child into their favourite character or adding whimsy to a corporate function, engaging a skilled face painter singapore provides demonstrates how art adapts to serve society’s evolving needs.

MIM Manufacturing: Revolutionising Modern Metal Production

MIM manufacturing is transforming how companies make complex metal parts with incredible accuracy and speed. Think of it as combining the best of plastic moulding with the strength of metal. This clever process lets manufacturers create shapes that were once impossible or too expensive to make.

What Makes MIM Manufacturing Special

Metal injection moulding works like magic. You can make tiny, detailed metal parts that would cost a fortune using traditional methods. While old-school techniques like machining struggle with complex shapes, MIM manufacturing makes them easily.

Here’s how it works in simple terms. First, ultra-fine metal powder gets mixed with plastic binders to create a mouldable paste. This mixture flows into moulds just like melted plastic would. After shaping, the plastic bits are removed and the metal is heated until it fuses together. The result? Solid metal parts as strong as those made through traditional methods.

The precision achieved through MIM manufacturing is remarkable. Parts can include features like tiny holes, thin walls, and complex curves all in one piece. Traditional manufacturing would need multiple operations to achieve the same result, adding time and cost to production.

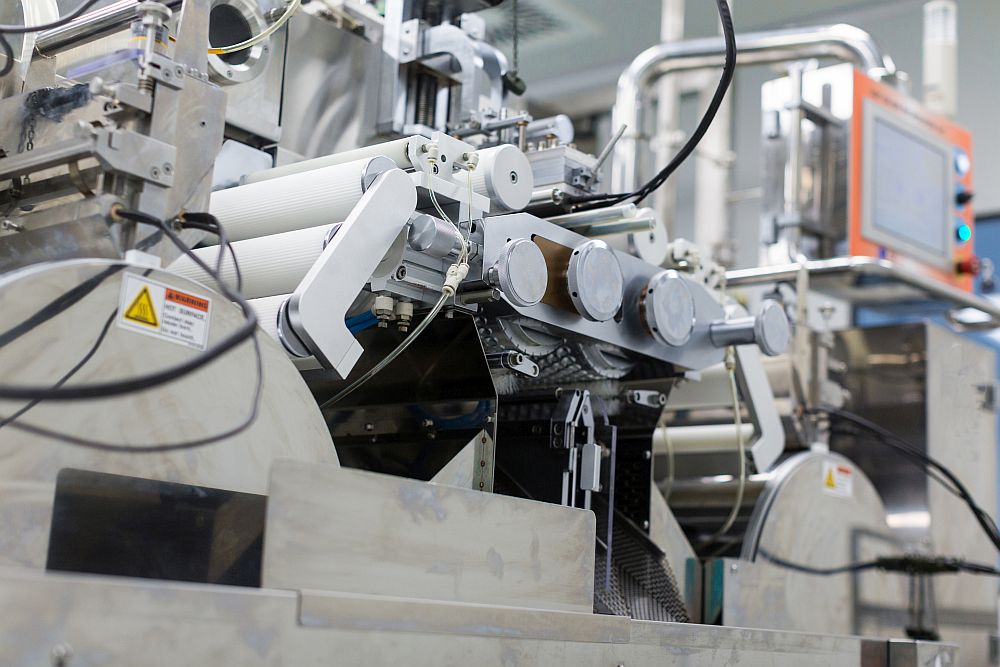
Close-up view of an industrial food processing machine, similar to those seen in MIM manufacturing, with a conveyor belt carrying jars for automated filling or packaging.

Why Choose the MIM Process

The benefits of MIM manufacturing go well beyond saving money. Here’s what makes it brilliant:

  • Create complex shapes with hidden features and internal threads 

  • Use over 97 percent of your raw materials with minimal waste 

  • Get smooth surfaces that don’t need extra finishing work 

  • Combine several parts into one single component 

  • Enjoy consistent strength throughout each part 

  • Save money on medium to large production runs

These advantages explain why medical companies love MIM manufacturing. They use it to make surgical tools and implants that must be both safe for the body and perfectly precise.

Materials You Can Use

MIM manufacturing works with many different metals. Stainless steel is the most popular choice, making up about half of all mim parts. But you can also use regular steel, tool steel, magnetic materials, tungsten, and even gold or silver.

This flexibility means different industries can benefit. Car makers use MIM manufacturing for turbocharger parts and fuel injectors. Electronics companies make connectors and heat sinks. Even luxury brands use it for watch parts and jewellery pieces.

The Asian Success Story

Asia has become a powerhouse in mim manufacturing. Industry experts note that “Singapore’s MIM manufacturing sector has experienced remarkable growth, with the country establishing itself as a regional hub for high precision metal injection moulded components, particularly for the medical and electronics industries.” This success story shows how investing in modern technology pays off.

What to Consider

Before jumping into MIM manufacturing, you need to know its limits. Parts usually weigh between 0.1 and 100 grams, though most are between 1 and 20 grams. Walls should be thinner than 6 millimetres to avoid problems during cooling.

The moulds can be expensive to make initially. That’s why MIM manufacturing works best when you need at least 10,000 pieces per year. But when you hit these numbers, the cost per part often beats traditional methods hands down, especially for complex shapes.

Keeping Quality High

Today’s MIM manufacturing facilities use smart technology to check quality. Computer systems monitor every step. Cameras inspect parts automatically. Measuring machines ensure everything meets specifications. Most parts stay within 0.3 to 0.5 percent of the intended size.

Global standards help maintain quality too. Industry groups have created guidelines for materials and processes. ISO standards provide rules for testing and quality management. These standards mean engineers can trust MIM parts for important applications.

Environmental Benefits

MIM manufacturing also helps the planet. The process creates very little waste compared to traditional machining, which often turns most of your raw material into scrap. Energy use is lower too, since you’re not cutting away material for hours on end. Many facilities now recycle their binder materials and reuse metal powder that doesn’t make it into parts. This eco-friendly approach appeals to companies trying to reduce their environmental footprint whilst maintaining high quality standards.

What’s Coming Next

The future of MIM manufacturing looks bright. Scientists are developing new binder materials that work faster and create less waste. Computer programmes now let designers test their ideas virtually before making expensive moulds.

3D printing is starting to work alongside MIM manufacturing. Companies can 3D print prototypes for testing, then use MIM for mass production. This combination speeds up development while keeping production costs low.

Making Smart Decisions

Choosing MIM manufacturing requires careful thought. You need to consider several factors:

First, look at your design complexity. The more intricate your part, the more sense MIM makes. Next, think about quantities. Higher volumes mean lower costs per piece. Consider your material needs too. Make sure MIM can work with your chosen metal.

Talk to MIM manufacturers early in your design process. They can help you adjust your designs to work better with the process. Small changes early on can save big money later.

The Bottom Line

MIM manufacturing keeps getting better. New materials appear regularly. Process improvements push the boundaries further. Quality keeps improving whilst costs keep dropping.

Companies that understand MIM manufacturing gain a real edge over competitors. They can make better parts faster and cheaper than ever before. As global competition heats up, smart manufacturers are turning to MIM to stay ahead.

Whether you’re making medical devices, car parts, or consumer electronics, mim manufacturing could be the key to better products at lower costs.


Unlock Your Business Dreams: Complete Funding Guide

For entrepreneurs navigating Singapore’s competitive landscape, understanding how to get a business loan represents the difference between watching dreams gather dust and witnessing them transform into thriving enterprises that employ neighbours and contribute to economic growth.

The Human Face of Business Financing

Behind every loan application sits a person with calloused hands from late nights building something from nothing, eyes tired from reviewing spreadsheets, and a heart heavy with the weight of employing others. These are Singapore’s small and medium enterprise owners, comprising over 99% of businesses, yet often finding themselves outside bank lobbies, wondering if their dreams merit institutional faith.

The statistics paint a stark reality: according to Enterprise Singapore surveys, over 65% of SMEs depend on business loans for growth. Yet for many, the path to securing financing remains shrouded in complexity and requirements that can feel impenetrable.

Decoding the Eligibility Maze

The journey begins with understanding what lenders seek in potential borrowers. Singapore’s financial institutions have established criteria that serve as gatekeepers to opportunity. These requirements, whilst logical from a risk perspective, can feel overwhelming to business owners who measure success in satisfied customers rather than credit scores.

To qualify for most business financing in Singapore, companies must meet several fundamental requirements:

•      Business registration with the Accounting and Corporate Regulatory Authority for at least six months to three years

•      Minimum 30% local shareholding held by Singapore citizens or permanent residents

•      Annual revenue thresholds, typically starting from $200,000 for traditional bank loans

•      Demonstrated operational history, with most lenders preferring businesses that have weathered at least two years of market conditions

The government recognises these barriers and has responded with the Enterprise Financing Scheme, which consolidates multiple lending programmes under one umbrella. As official documents state, “Enterprise Singapore will share the loan default risk in the event of enterprise insolvency with the Participating Financial Institutions,” effectively encouraging banks to extend credit to businesses that might otherwise struggle to secure funding.

The Documentation Journey

For many business owners, gathering the required paperwork feels like preparing for a financial audit rather than securing growth capital. Yet each document tells part of their company’s story, painting a picture of resilience, ambition, and potential that underwriters must decipher from balance sheets and cash flow statements.

Essential documentation typically includes business registration certificates, financial statements covering the past two to three years, bank statements demonstrating cash flow patterns, personal income tax assessments for directors, and detailed business plans outlining how borrowed funds will generate returns. The Credit Bureau Singapore report also plays a crucial role, as personal credit histories of business owners significantly influence approval decisions.

What strikes many applicants as particularly challenging is how their financial behaviour becomes inseparable from their business prospects. A missed credit card payment from years past can derail expansion plans, whilst consistent personal financial management opens doors to institutional support.

Government Support: A Lifeline for Growth

Singapore’s approach to supporting small businesses extends far beyond traditional banking channels. The Enterprise Financing Scheme represents a comprehensive toolkit designed to address financing needs across different growth stages. The SME Working Capital Loan, recently enhanced to offer up to $500,000, provides operational cash flow support with government risk sharing that encourages lender participation.

These programmes acknowledge a fundamental truth about small business lending: traditional risk assessment models often fail to capture the true potential of innovative enterprises. By sharing default risk, the government creates space for lenders to support businesses that might not meet conventional criteria but possess the vision and determination to contribute meaningfully to Singapore’s economic future.

The scheme encompasses multiple financing categories, from working capital loans supporting daily operations to fixed asset financing enabling equipment purchases, and even merger and acquisition loans facilitating business consolidation or expansion into new markets.

Navigating Interest Rates and Terms

Business loan interest rates in Singapore typically range from 7% to 9% per annum for unsecured facilities, though rates vary significantly based on business profiles, industry sectors, and loan terms. Government-assisted schemes often offer more favourable rates due to risk-sharing arrangements, making them particularly attractive to qualifying businesses.

The loan approval process, whilst often consuming several weeks, reflects the careful evaluation lenders undertake to balance risk with opportunity. During this period, businesses continue operating in uncertainty, unable to commit fully to expansion plans or strategic initiatives until funding confirmation arrives.

Beyond Traditional Banking

For businesses unable to secure traditional bank financing, Singapore’s financial ecosystem offers alternative channels. Licensed money lenders provide more flexible approaches to business funding, whilst peer-to-peer lending platforms connect entrepreneurs directly with individual and institutional investors willing to support promising ventures.

These alternatives typically come with higher interest rates and shorter repayment terms, but they also offer faster approval processes and more personalised evaluation criteria that consider factors beyond traditional financial metrics.

The Path Forward

Success in securing business financing requires preparation, patience, and often, professional guidance. Business owners who approach the process strategically, maintaining clean financial records, developing comprehensive business plans, and building relationships with potential lenders, significantly improve their approval prospects.

The most successful applicants understand that loan applications are not merely transactional exchanges but opportunities to communicate their vision, demonstrate their competence, and invite financial institutions to participate in their growth stories.

For Singapore’s entrepreneurs, persistence often proves as valuable as perfect paperwork. Many successful businesses were built by founders who faced initial rejections but refined their approaches, strengthened their financial positions, and eventually secured the funding needed to transform their visions into reality.

In a nation built on entrepreneurial spirit, learning how to get a business loan becomes an essential skill for anyone ready to contribute their chapter to Singapore’s continuing success story.


When Life Demands Cash Now: Why Singapore’s Smart Money Moves Include an Urgent Cash Loan Today

The moment arrives without warning—a medical emergency, a sudden job loss, or an unexpected repair bill that threatens to derail your carefully planned budget. In Singapore’s fast-paced financial landscape, where 61% of adults feel they live paycheck to paycheck despite the city-state’s economic prosperity, securing an urgent cash loan today has become not just a convenience but often a necessity for navigating life’s unpredictable turns.

The Economics of Emergency: Singapore’s Financial Reality

Singapore’s economic story in 2024 reads like a tale of two cities. On one surface, consumer sentiment has brightened considerably—68% of Singaporeans feel positive about the current economic environment, marking a remarkable 20-percentage-point surge from the previous year. Yet beneath this optimism lies a more complex narrative. The Monetary Authority of Singapore reports that total loans reached $960.210 billion in January 2025, reflecting not just economic growth but also the increasing reliance on credit to bridge financial gaps.

The statistics paint a picture that would have fascinated social historians like myself: a society where 92% maintain emergency funds, yet only 60% have saved enough to cover three months of expenses. This gap between aspiration and reality creates fertile ground for the urgent cash loan market—a space where immediate financial needs collide with longer-term financial planning.

Navigating the Immediate Cash Loan Landscape

When seeking fast cash loans today, Singapore’s borrowers face a competitive marketplace where traditional banks offer personal loan rates ranging from 1.99% to 3.80% annually. The archipelago’s financial institutions have evolved to meet the demands of a population where nearly two-thirds feel financially stretched, despite living in one of the world’s most prosperous nations.

The appeal of same-day cash loans extends beyond mere convenience. In a society where consumer spending is projected to grow at 2.8% in 2024—a modest increase reflecting inflationary pressures—the ability to access emergency funds can mean the difference between maintaining stability and facing financial catastrophe. Consider these scenarios where instant cash advances become essential:

  • Medical emergencies that exceed insurance coverage, particularly relevant given Singapore’s ageing population, where nearly half of emergency medical calls involve seniors aged 65 and above 

  • Job transition periods where savings must stretch between employment opportunities 

  • Educational expenses that arise unexpectedly, affecting 11% of families reporting increased spending on child education 

  • Home maintenance crises that cannot wait for traditional loan approval processes

The Psychology of Quick Money Solutions

What strikes me most about Singapore’s relationship with emergency financing is the psychological dimension. The UOB Consumer Sentiment Study reveals that one in three borrowers with loan liabilities actively pay additional amounts to reduce their loan tenure—a behaviour that suggests sophisticated financial planning coexisting with immediate credit needs.

This phenomenon reflects what economists might call “temporal financial segmentation”—the ability to simultaneously manage long-term wealth building while addressing short-term liquidity crises. It’s a financial behaviour that mirrors Singapore’s broader economic strategy: maintaining stability while remaining agile enough to respond to immediate challenges.

Strategic Borrowing in the Digital Age

The infrastructure supporting rapid cash disbursement has evolved dramatically. With over 90% of Singapore’s stores accepting SGQR digital payments, the financial ecosystem has adapted to support instant transactions. This technological foundation enables lenders like CashMax Credit to offer streamlined approval processes that can match the speed of Singapore’s digital-first economy.

The key to successful emergency borrowing lies in understanding the total cost of quick access to funds. While advertised rates may start from attractive levels, the Effective Interest Rate (EIR) provides a more complete picture of borrowing costs. Smart borrowers evaluate not just the speed of access, but the long-term implications of their financial decisions.

What You Need to Know About Payday Loans in 2024

In today’s fast-paced financial landscape, payday loans have become an increasingly common solution for Singaporeans facing temporary cash flow challenges. As a credit analyst with extensive experience in consumer lending, I’ve witnessed firsthand how these short-term financial tools can either solve problems or create them – depending entirely on how they’re used and understood.

The Reality of Short-Term Borrowing

Let’s cut through the noise and get to what matters. According to recent Ministry of Law statistics, approximately 300,000 Singaporeans explore short-term lending options annually. Why? Because life doesn’t always align with payday schedules. Medical emergencies, urgent repairs, or unexpected opportunities don’t wait for your next salary credit.

Understanding the True Cost

Here’s what most lenders won’t tell you upfront: The effective interest rate on short-term loans can vary dramatically. Licensed lenders in Singapore are bound by law to cap their interest at 4% monthly. However, the total cost of borrowing includes:

– Administrative fees (maximum 10% of principal)

– Late payment charges

– Legal fees for loan documentation

– Early settlement fees

Expert Tip: Calculate your total repayment amount before signing. A $1,000 loan could cost you $1,140 over one month when all fees are included.

Who Actually Qualifies?

Based on my analysis of thousands of applications, here’s what really matters:

– Minimum monthly income of $1,500 for Singaporeans/PRs

– Stable employment history (at least 3 months)

– Clean credit record with no recent defaults

– Age between 21 and 65 years

The Hidden Advantages

Few people realise this, but short-term loans can actually benefit your credit profile when managed correctly. Credit Bureau Singapore data shows that 72% of borrowers who maintain perfect repayment records see an improvement in their credit score within three months.

Warning Signs to Watch

My years of credit analysis have revealed these red flags:

– Lenders who advertise through WhatsApp or SMS

– Requests for upfront fees

– Pressure to borrow more than requested

– Unclear or verbal-only terms

– Reluctance to provide detailed loan contracts

Expert Tip: Always verify a lender’s license number on the Ministry of Law’s website. Legitimate lenders prominently display their license numbers.

Smart Borrowing Strategies

Here’s what successful borrowers do differently:

  1. Borrow only what’s absolutely necessary
  2. Calculate total repayment costs before accepting
  3. Create a dedicated repayment fund
  4. Keep all loan documentation
  5. Communicate proactively with lenders if issues arise

The Application Process Decoded

Want to speed up your approval? Focus on these key elements:

– Complete and accurate documentation

– Clear purpose for the loan

– Realistic repayment plan

– Transparent disclosure of existing commitments

Understanding Repayment Options

Recent data shows that 88% of successful repayments involve:

– Automated bank transfers

– Salary deduction arrangements

– Regular electronic payments

– Early repayment when possible

Expert Tip: Set up automatic payments scheduled for your payday to avoid late fees and maintain a perfect repayment record.

Impact on Your Financial Future

Here’s what most people don’t realise: Short-term loans can affect your:

– Future borrowing capacity

– Credit score

– Banking relationships

– Employment opportunities

Making an Informed Decision

Consider these crucial statistics:

– 94% of licensed lender borrowers successfully repay their loans

– The average processing time is under 2 hours

– 85% of borrowers cite emergency expenses as their primary reason

– 76% repay within the agreed timeline

Building Financial Resilience

The smartest approach to short-term loans includes:

– Creating an emergency fund (aim for 3 months’ expenses)

– Understanding all available options

– Maintaining open communication with lenders

– Developing a long-term financial plan

Looking Ahead

The lending landscape in Singapore continues to evolve, with digital solutions making the process more efficient and transparent. However, the fundamentals of responsible borrowing remain unchanged. Understanding your rights, obligations, and options is crucial for making informed financial decisions.

Remember, short-term loans can be valuable financial tools when used responsibly. Based on my analysis of thousands of cases, success depends on choosing the right lender, understanding the terms, and having a solid repayment plan. If you’re considering a payday loan singapore, ensure you work with a licensed lender and thoroughly understand the terms before proceeding.